The freight markets in the Northwest and Midwest exhibit significant divergence, with rejection rates in the Northwest soaring due to a surge in reefer demand, while the Midwest remains consistently tight.
Chart of the Week: SONAR Regional Tender Rejection Rates SONAR: STRI.URMW, STRI.URNW, STRI.URSE, STRI.URSW, STRI.URNE
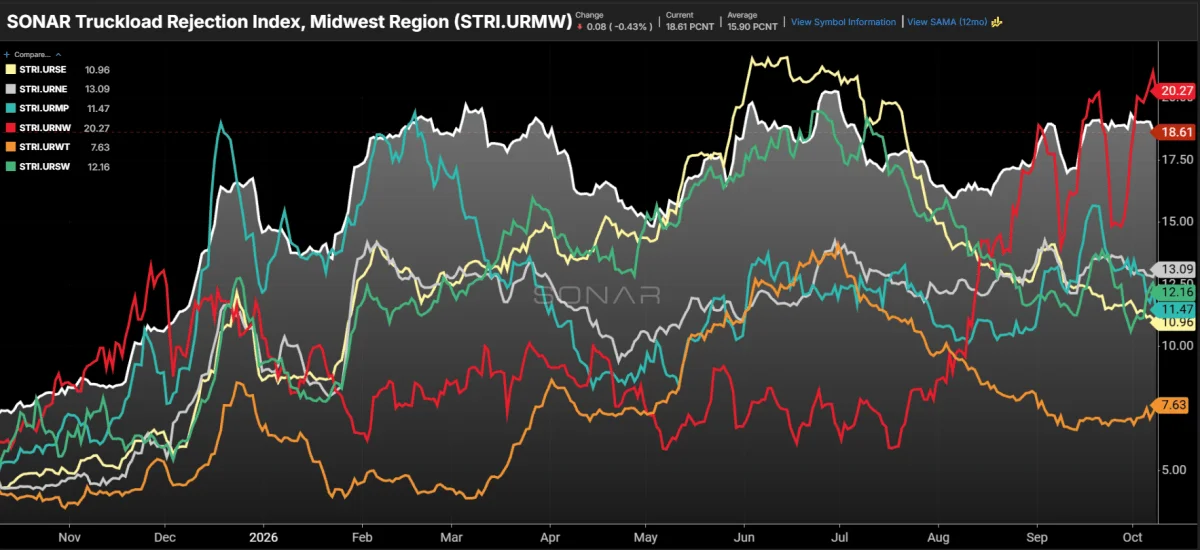
Recent data indicates that national tender rejections have softened to approximately 13.8% over the past two weeks. However, this average conceals a more complex picture of the freight market, which is currently experiencing a split in its dynamics. The Northwest region's tender rejection rate surged to 20.27% on October 8, an alarming increase from the 6.2% recorded the previous year, marking it as the highest rejection rate among all regions. The Midwest is following closely with a rejection rate of 18.61%, significantly higher than last year and indicative of sustained tightness.
Northwest's Rapid Shift and Reefer Demand
Throughout the early part of 2026, the Northwest was characterized by a relative loosening in its freight capacity, with rejection rates fluctuating between 6% and 9% from January to July. This trend took a drastic turn in August, as rejection rates nearly doubled and have continued to rise weekly. The driving force behind this increase is predominantly the reefer sector, where rejection rates have soared to an average of 41% in October, compared to approximately 17% in July and a mere 16% in October of the previous year. Meanwhile, van rejections remain low, at under 5%.
Interestingly, reefer tender volume has surged by 65% since July and is 35% higher than a year ago. In contrast, van volumes have decreased by 11% compared to the previous year. This shift points to a significant structural change within the Northwest's freight market.
Harvest Dynamics with Limited Fleet Capacity
The timing of the surge can be attributed to the autumn harvest season for produce, particularly apples and potatoes, which are harvested extensively in Washington, Oregon, and Idaho from late August through October. This freight typically requires reefer trucks. While this seasonal spike in demand was somewhat expected, it has occurred earlier and is more pronounced than previous patterns. Last year's harvest did not witness rejection rates exceeding 10% until mid-November, peaking at around 13%.
Despite a robust seasonal demand, the size of this year's harvest is not a significant catalyst for the higher rejection rates. The USDA projects a 2% decline in Washington's apple crop for 2026, totaling around 176.2 million bushels, with a national crop expected to drop by 7%. Thus, the impact on supply appears more pronounced due to a thinner fleet than an actual surge in product volume.
Midwest: Persistent Tightness Amid Growth
Conversely, the Midwest region has maintained a rejection rate hovering around 15% since February and currently sits at 18.6%. This marks a stark rise from the 7.6% rejection rate recorded last October. Notably, tender volumes in the Midwest have increased by roughly 10% year-over-year, which is higher than the 8% national average. Unlike the Northwest, the tightness in the Midwest is affecting multiple equipment types, with van rejections reaching nearly 15%—approximately two and a half times higher than last year's levels—and reefer rejections climbing to close to 29%, an increase from 15% last year.
Implications for the Freight Market
The situation in the Northwest illustrates a regional demand surge influenced by volatility, alongside a notable decrease in national capacity compared to the previous year. For a significant part of the year, the Northwest has produced limited outbound freight, which leads carriers to minimize contract commitments to avoid being trapped in a market with little escape. As harvest season ramps up, however, the sudden increase in freight demand has exposed the inadequacies of regional capacity.
In contrast, the Midwest region plays a crucial role in shaping the national freight picture due to its size and volume. Operating at rejection rates approximately five points above the national average while still exhibiting volume growth signals ongoing issues for carriers in maintaining tender compliance. Despite the easing national landscape, the continued high rejection rates in the Midwest indicate a broader, long-term trend rather than a transient issue.
Additionally, regions such as the Southeast and Southwest are adapting by turning to intermodal solutions, with domestic intermodal volumes through major hubs like Atlanta and Dallas reportedly increasing by 15% to 20% year-over-year. This trend gained momentum during the summer when rejection rates rose.
About the Chart of the Week
The FreightWaves Chart of the Week, curated from SONAR data, showcases a pivotal data point that reflects the current state of the freight markets. Each week, a selection from thousands of charts is made to provide insights into real-time market conditions, bolstered by expert commentary. After publication, these insights are archived at FreightWaves.com for future reference.
SONAR consolidates a multitude of data sources, presenting information visually to support industry participants’ understanding of real-time market dynamics. The data science and product teams at FreightWaves are continually producing new datasets, enhancing the client experience.
To learn more or request a SONAR demo, click here.
The post The two tightest regions tell two very different stories about the freight market originally appeared on FreightWaves.