Trucking rates are rising due to a decrease in capacity rather than increased freight volume, with operational costs significantly impacting profitability.
In 2026, truckload rates are showing marked increases primarily due to a decline in the number of operational trucks rather than an uptick in freight demand. Carriers have faced three challenging years where they've had to transport goods at rates that often didn't cover operational costs. This period of sustaining low rates is now yielding to a necessary adjustment, as highlighted in SONAR’s latest report, The Repricing Isn’t Finished, indicating that the market has only partially corrected thus far.
Current Truck Operating Costs
The American Transportation Research Institute (ATRI) recently released its 2026 study, revealing that the cost of operating a truck has reached an unprecedented high of $2.336 per mile in 2025, representing a 3.4% increase from the previous year. When fuel costs are excluded, operational expenses climbed an even steeper 4.2%, outpacing inflation by 1.5 percentage points.
Many categories of expenses have hit all-time highs, including tolls (+13.2%), repairs and maintenance (+8.6%), driver benefits (+6.6%), and tires (+6.4%). Early in 2026, insurance costs surged by 6.4%, while fuel prices saw a notable rise of 5.9%, with SONAR’s diesel index currently at $6.38 per gallon. These rising costs further strain operators' margins and inevitably contribute to the increase in truckload rates.
Rate Insufficiency Against Rising Costs
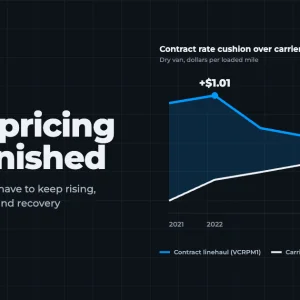
From a broader perspective on rates, SONAR's data indicates that the average contract linehaul rate for dry van freight (referred to as VCRPM1) averaged $2.81 per mile in 2022. However, by 2024 and 2025, this rate diminished to around $2.32 per mile. Meanwhile, from 2021 to 2025, non-fuel costs for truckload carriers surged by 30%. In 2022, carriers had an average surplus of about $1.01 per loaded mile to cover non-fuel costs, but this cushion narrowed dramatically by 2025 to just $0.26.
- Contract linehaul rates fell beneath the threshold to cover non-fuel costs persistently from 2023 through 2025.
- As of Q3 2026, contract linehaul rates averaged $2.69, representing an improvement but still below Q4 2021 levels and only about half of the cushion held in 2022.
Understanding Rising Rates in Flat Demand Conditions
Interestingly, the rise in rates is occurring amid flat freight demand. The SONAR tender rejection index (STRI) has surged by 268% since October 2023, while tender volumes have only increased by about 9%. This divergence suggests that the loss of truck capacity is outpacing the available freight, with roughly 51,000 for-hire tractors exiting the market in a single month alone. ATRI reported that effective capacity was reduced by approximately 5.5% in 2025, a scenario characterized as a supply-side recovery.
Operational Limitations and Rate Adjustments
Given the current economics of trucking, carriers are unable to simply increase the number of miles driven to offset costs. SONAR’s analysis of a typical dry van truck at the Q3 2026 benchmark rates reveals that while it covers marginal costs, it contributes merely 15% of its revenue towards overhead expenses. Comparatively, ATRI reported that truckload carriers required roughly 26% of their revenues to cover overhead costs in 2025. To bridge this gap, rates would need to see an increase of about 14%. Moreover, even pushing near the maximum hours of service permissible, the truck would still fall approximately 5% short in terms of revenue generation.
Insights from SONAR's Sitrep Report
SONAR’s comprehensive report provides additional insights and analyses, including:
- A breakdown of rate discrepancies by mode, particularly noting that reefer contract rates are lagging significantly behind the market standards.
- Detailed market-level rejection data that illustrates where carriers are actively adjusting rates.
- An analysis of the freight lane from Chicago to Atlanta, including SONAR’s forecasts extending into 2027.
- An interactive tool that allows users to evaluate contract versus spot rates simulations, considering miles, diesel prices, and deadhead mileage against operational costs.
- Strategic takeaways for shippers, carriers, and brokers as they prepare for 2027 bidding cycles.
For further details, the SONAR platform hosts all relevant Sitrep reports and the data referenced throughout this analysis. Interested parties can also request a demo or explore options through the FreightWaves Market Monitor.
FAQs on Rising Truckload Rates
Why are truckload rates ascending in 2026? The market is seeing a reduction in truck capacity outpacing the demand for freight, causing significant increases in competitive dynamics among fewer players.
What are the operational costs associated with trucking per mile? According to ATRI’s report, the study shows the average operational cost in 2025 clocking in at $2.336 per mile, or $1.854 when excluding fuel.
Are trucking rates considered high right now? Presently, trucking rates remain comparatively lower given the sharp rise in non-fuel operating costs, with dry van contract linehaul averaging just $2.69 in Q3 2026.
Will truckload rates continue to rise? Current calculations suggest they must increase to meet operational costs; the rates need to adjust further for sustainability as indicated by SONAR's projections into 2027.
What does tender rejection rate signify? This term denotes the percentage of contracted loads that carriers decline. The STRI index from SONAR tracks this figure, and an increase suggests carriers are opting for more lucrative options than their existing contracts.
Sources: SONAR (VCRPM1, NTIL, NTI, STRI, STVI, DTS, TCFH); ATRI.