Despite rising tender rejections, new trucking capacity remains stagnant into 2026, influenced by rising costs and a shortage of compliant drivers.
The Short Answer
As of October 2026, the introduction of new trucking capacity into the freight market is stagnating, reversing trends seen in previous cycles. Data from SONAR indicates that the number of tractors in fresh for-hire fleets has decreased to 19,520 as of August 2026. Concurrently, the SONAR Truckload Rejection Index (STRI) remains elevated near 14%, approximately three times higher than the average observed between 2023 and 2025.
Historically, heightened rejection rates have prompted an influx of new vehicles into the market within just a few quarters. However, that pattern has not materialized this time. While there is growth in operating authority counts, these figures do not directly translate to truck numbers. SONAR's recent report titled The Authority Illusion elaborates on these trends.
Key Takeaways
- New capacity is contracting, not expanding. The count of tractors in new for-hire fleets fell by approximately 14% from the first half of 2026.
- Rejections have surged significantly. They increased by 268% over three years, while freight volume only grew by 9%, indicating a tightening market due to the loss of trucks rather than increased demand.
- Authority counts don’t accurately reflect capacity. Although new operating authority additions are at five-year highs, they are largely attributed to the rollout of FMCSA’s Motus registration system, and actual new truck grants are about 17% lower than in early 2026.
- Fewer new carriers are launching operations. Only about two-thirds of new interstate registrants currently secure liability insurance, a marked decline from over 90% in 2019.
- Expect tight market conditions through early 2027. Increasing insurance costs alongside a smaller pool of compliant drivers are contributing to the absence of new capacity.
How This Freight Cycle Differs from 2020–2022
The current freight cycle contrasts sharply with the one experienced between 2020 and 2022, where new capacity responded promptly to price signals. During that period, the STRI spiked in mid-2020, leading to an increase in new for-hire fleet tractors that peaked at roughly 47,000 in mid-2022.
In stark contrast, the current cycle has seen new fleet tractors decline from that peak. After reaching a low early in 2025, counts ticked upward in spring but have since plateaued. Following a sharp increase in the STRI starting in fall 2025, the count of new-fleet tractors has continued to decrease. Notably, there was a drastic fall of about 51,000 for-hire tractors recorded in August 2026 alone.
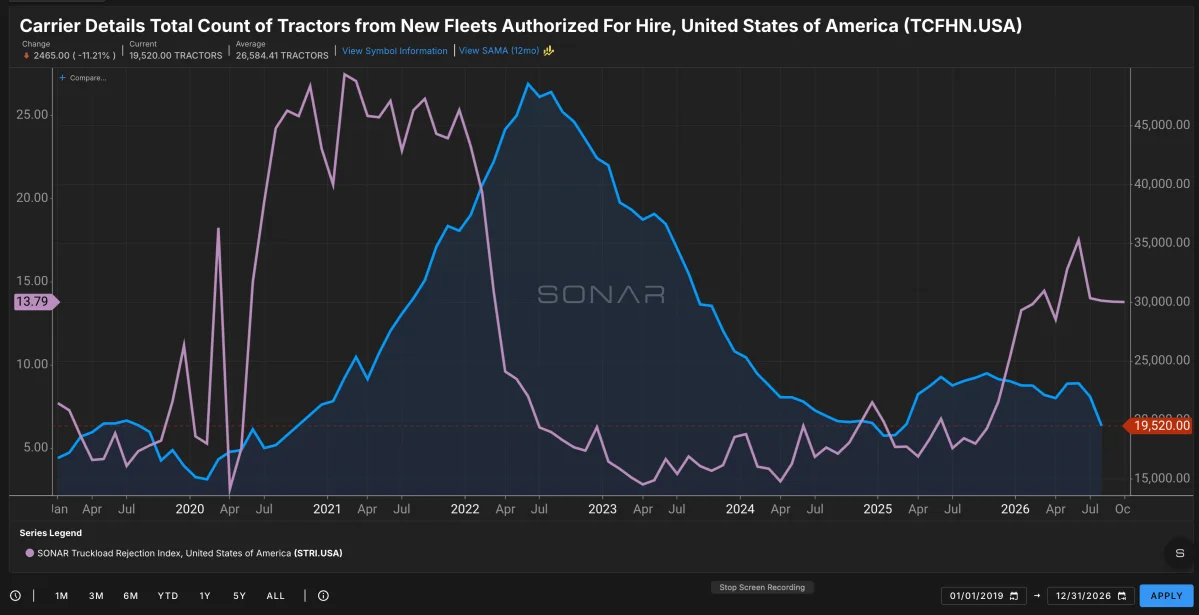
Tender rejections have risen significantly in 2025–2026 while the number of tractors in new for-hire fleets has decreased.
Truckload Freight Volume Trends
Demand for truckload freight has barely shifted, with the SONAR Truckload Volume Index (STVI) only rising 9% over three years ending in October 2026. Meanwhile, tender rejections skyrocketed by 268%. At their peak in early summer 2026, these rejections had soared over 350%.
If demand were a primary driver, we would expect these two metrics to correlate more closely. Instead, the substantial rejection rates indicate that carriers are opting to turn down nearly four times the number of loads while handling nearly the same freight volume. This situation typically would see a correction as new trucks enter the market, but that correction hasn't occurred. The American Transportation Research Institute (ATRI) concurs, highlighting the sparse supply-side recovery happening in 2026.
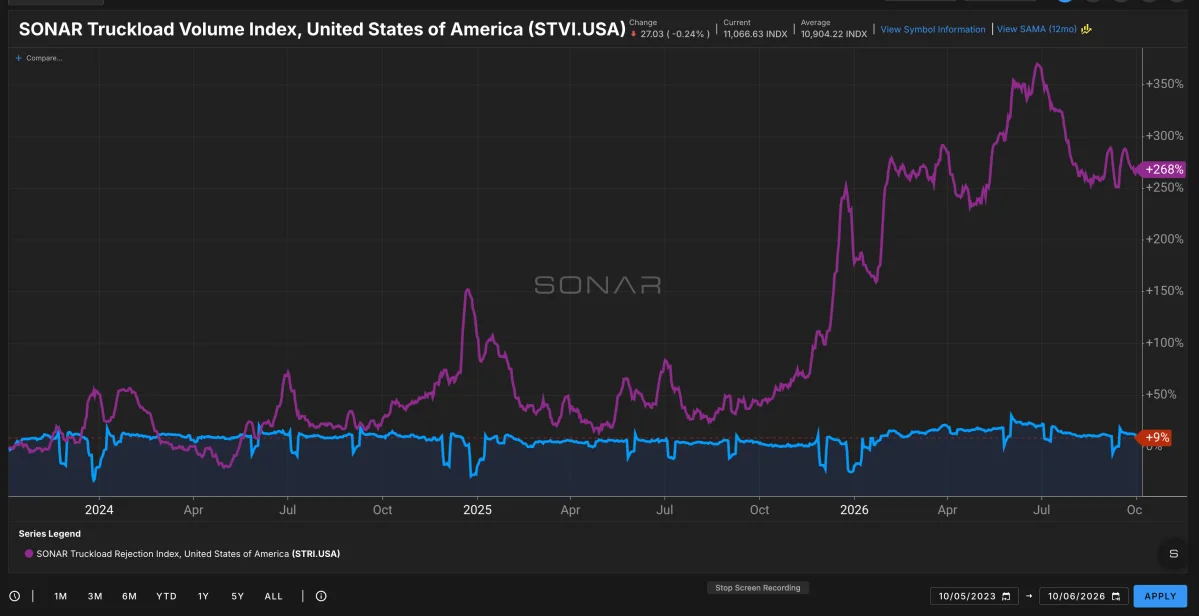
Truckload volume has increased by 9%, while tender rejections have surged by 268% over three years.
Understanding the Surge in Trucking Authorities
The increase in trucking authorities is noteworthy. An operating authority represents permission to operate, not a representation of the number of trucks a company owns. For instance, both a single-owner operator and a large fleet of 5,000 trucks would each count as one authority. Between 2019 and 2022, there was a 51% increase in total authorities, compared to only a 12% rise in for-hire tractors.
The recent spike in 2026 authorities is largely administrative. During late August and September, net authority additions surpassed 2,000 weekly, the highest recorded in five years. This was influenced by FMCSA’s new Motus registration system, which paused deactivations while clearing a backlog of applications and reinstatements. Consequently, revocations were outpaced by reinstatements for the first time since at least 2019, although the estimated new authority grants dropped about 17% below the first quarter levels.
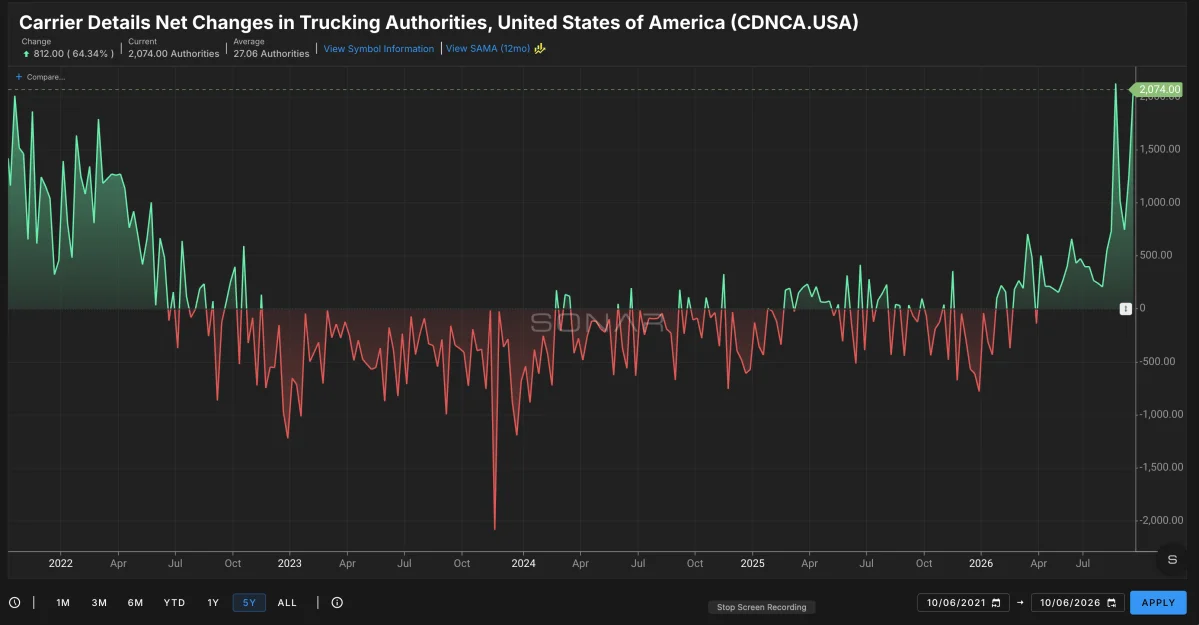
Weekly net authority additions spiked above 2,000 in late 2026.
Barriers to New Trucking Capacity
Several factors are raising the cost of entry into the trucking market. These include:
- Reduced pool of compliant drivers. As of January 2, 2026, over 202,000 CDL and permit holders were in prohibited status within FMCSA’s Drug and Alcohol Clearinghouse. New rules, including a non-domiciled CDL enforcement that will extend to a significant number of drivers, are also contributing to this issue.
- Increasing insurance premiums. In 2025, liability and cargo insurance costs rose by 3.9%, landing at around 10.6 cents per mile, despite a decline in crash rates. Insurance costs continued to rise through early 2026, further complicating matters for new carriers.
- Minimal profit margins. Operating margins for truckload firms barely broke even in 2025, complicating any decision to expand fleets.
These pressures are also impacting larger carriers. Companies like Schneider expressed challenges with driver constraints in their second-quarter 2026 earnings, while Knight-Swift and Werner acknowledged that driver availability continues to limit their operational capacity.
Future Market Expectations
Shippers should anticipate a tight truckload market continuing into early 2027, with STRI remaining significantly above the 4% to 6% range typically seen between 2023 and 2025. Notably, ATRI identified that about 10% of carrier trucks were parked without drivers in 2025, meaning they could re-enter the market only if compliant drivers can be secured.
The early indicators of any market shift will likely include:
- Consistent increases in tractor counts and new fleet trucks over multiple months
- A reduction in STRI accompanied by stable STVI levels
- A rise in first-time insurance filings, compared to authority counts
Frequently Asked Questions
Is trucking capacity growing in 2026? No, metrics indicating active trucks are declining—total for-hire tractors decreased by about 51,000 in August 2026, while fleets reporting miles are at their lowest since early 2020.
What constitutes a trucking operating authority? An operating authority, or MC number, is the FMCSA's permission for a company to haul regulated freight across state lines. It does not indicate the number of operational trucks.
Why are tender rejections elevated despite flat freight volume? The increase in tender rejections is attributed to diminished capacity, as carriers are rejecting a higher volume of loads in response to fewer trucks and compliant drivers.
What are the best indicators of actual trucking capacity? The most reliable indicators are tractor counts, fleets actively reporting miles, and tender rejection rates, with new insurance filings serving as a better measure of new market entries than authority counts.
What caused the negative net revocations in 2026? The FMCSA’s Motus system rollout paused deactivations and processed outstanding applications, resulting in more reinstatements than revocations, indicating an administrative effect rather than an influx of new carriers.
Read the Full Sitrep
The comprehensive report The Authority Illusion provides an in-depth look at authority, tractor, insurance, and registration data, along with a capacity scorecard for 2026 and indicators shippers should monitor. For detailed insights, view the full Sitrep through the FreightWaves Market Monitor or the SONAR platform.
For real-time tracking of tender rejections, volumes, and carrier fleet data, consider subscribing to SONAR.
Sources: SONAR (STRI, STVI, TCFHN, TCFH, CDNCA, CDNR, ELPVOOS); ATRI, An Analysis of the Operational Costs of Trucking: 2026 Update; FMCSA Drug and Alcohol Clearinghouse Monthly Report, December 2025; Transport Topics, Schneider expects supply reduction momentum through 2026; FMCSA Licensing & Insurance and Company Census data.